
Disclaimer: This newsletter is not financial advice it is for educational purposes only. Please DO NOT take this newsletter as a buy or sell signal.
Jumbo S.A. Fundamentals:
Below is a checklist I normally use when analysing a company’s fundamental health. If the company meets my criteria it will be colour-coded in green and if it fails to meet my criteria it will be colour-coded in red which means I need to investigate further and ask myself why this is the case.
As you can see below there are 2 red boxes and I am going to explain them:
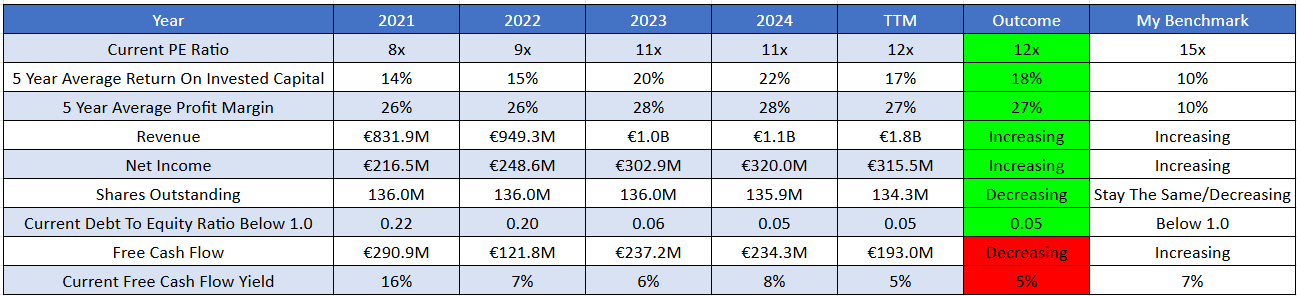
Free Cash Flow- Free cash flow (FCF) is a financial metric that measures the cash a company generates from its operations after accounting for capital expenditures. Companies can use their cash flow in various ways including reinvesting in the business, paying dividends, reducing debt, or repurchasing stock. When free cash flow is negative it usually indicates that a company is spending more on capital expenditures than it earns from its core operations. Jumbo S.A.'s free cash flow has declined in the last five years due to the company's strategic shift towards investments in its retail stores and logistics infrastructure.
Free Cash Flow Yield- Free Cash Flow Yield gives investors another way to assess a company's value. Free cash flow yield provides a better measure of a company’s performance than the P/E ratio because earnings can be manipulated based on accounting rules. The most common way to calculate free cash flow yield is free cash flow divided by the company’s market cap. The lower the ratio the less attractive a company is as an investment because investors are putting money into the company but not receiving an excellent return. A high free cash flow yield implies that a company generates enough cash to quickly satisfy its debt and other obligations including dividend payout. Jumbo S.A.'s free cash flow yield is 5% which is lower than my 7% threshold and higher than the risk-free rate which is currently at 3.9%. It is important to remember that when the treasury yield is lower than a company’s earnings/cash flow according to the intelligent investor you are being compensated for the extra risk you are taking with an individual business which shows there is some margin of safety with this investment. Lastly even though Jumbo S.A. currently has a free cash flow yield of 5% it doesn't tell the whole story because the company goes through a regular growth capex cycle which is why I like to analyse the company based on its operating cash flow. Currently Jumbo S.A. has an operating cash flow yield of 8%.
Business Overview:
Founded in 1986 by Apostolos Vakakis, Jumbo S.A. is a Greek retailer whose primary business involves the retail sale of toys, baby items, gifts, household goods, stationery, seasonal products, home décor, books, and other related items. Headquartered in Athens, Jumbo S.A. operates throughout Greece, Cyprus, Bulgaria, and Romania through large physical hyperstores and its online platform e-jumbo. The company also runs a small-scale wholesale business for toys and similar products.
Business Segments:
Home products- The home products segment has grown to become Jumbo S.A.'s largest and most profitable category that accounts for 39.1% of the company's revenue. This segment includes a broad range of decorative and household items, kitchenware, and other home essentials.
Seasonal products- Jumbo S.A. seasonal products make up 23.4% of the company’s revenue. This segment is a significant driver of sales especially during peak retail periods such as Christmas, Easter, and the back-to-school season. The company leverages these periods through in-store displays and marketing campaigns. Effective forecasting and inventory control are crucial for managing seasonal fluctuations.
Toys- This is the company’s original business. Toys remain a core part of their brand identity that accounts for 18.8% of the company's revenue. Jumbo S.A. remains a leading toy distributor in Greece by offering a wide range of toys at competitive prices.
Snacks, Candies, and Other Mini-Market Products- This segment primarily consists of snacks, sweets, and other mini-market items. This segment accounts for 8.5% of the company's revenue. These products are often strategically placed to encourage impulse purchases and increase the average transaction value.
Stationery- The stationery segment provides a steady revenue stream throughout the year with sales increasing during the back-to-school season. Stationary accounts for 7.5% of the company’s revenue. Products include writing instruments, notebooks, school supplies, and office supplies
Baby Products- This is Jumbo S.A.'s smallest segment that accounts for 2.7% of the company's revenue. This segment serves a strategic purpose by catering to young families which is a key demographic that also purchases toys.
Management:
When evaluating management I judge the CEO based on several factors such as experience, capital-allocation skills, and Incentives. In this section I will discuss whether management incentives are aligned with shareholders.
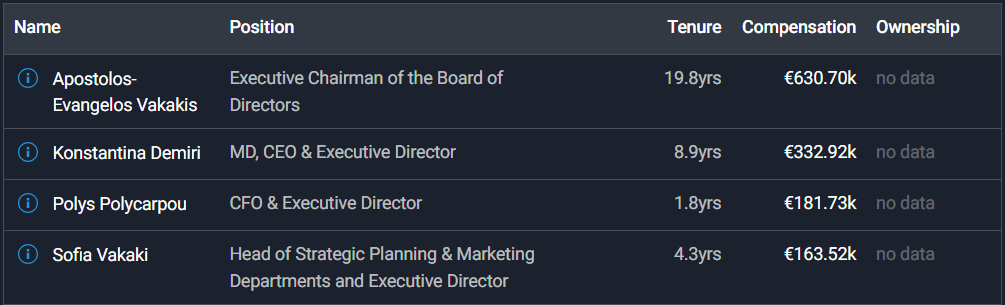
Experience- Konstantina Demiri is the Chief Executive Officer (CEO) and an Executive Director at Jumbo S.A. a position she has held since November 2016. Before Konstantina Demiri became the CEO of Jumbo S.A. she served as Jumbo S.A.’s Head of the Accounting Department from 2003 and later as their Chief Financial Officer (CFO). Her career before joining Jumbo S.A. included over 20 years as a financial controller for a major supermarket group in Greece. Konstantina Demiris is responsible for executing the company’s corporate strategy and managing day-to-day operations under the guidance of founder and Chairman Apostolos Vakakis. Her deep financial knowledge and long tenure at Jumbo S.A. provide stability and continuity for the company.
Below is an image illustrating the current experience of Jumbo S.A. board members:
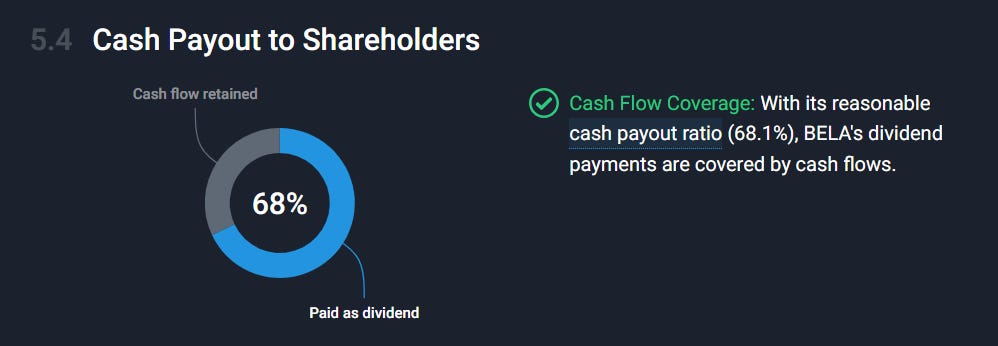
Capital Allocation- Capital allocation is very important when judging management because I want them to create value for shareholders not destroy it. So far Jumbo S.A. has done a great job with capital allocation because they are providing value back to shareholders by reinvesting in the business to further expand their presence and paying dividends.
Jumbo S.A. currently pays a dividend with a yield of 1.88%. This dividend is sustainable because it only covers 68% of the company’s free cash flow.
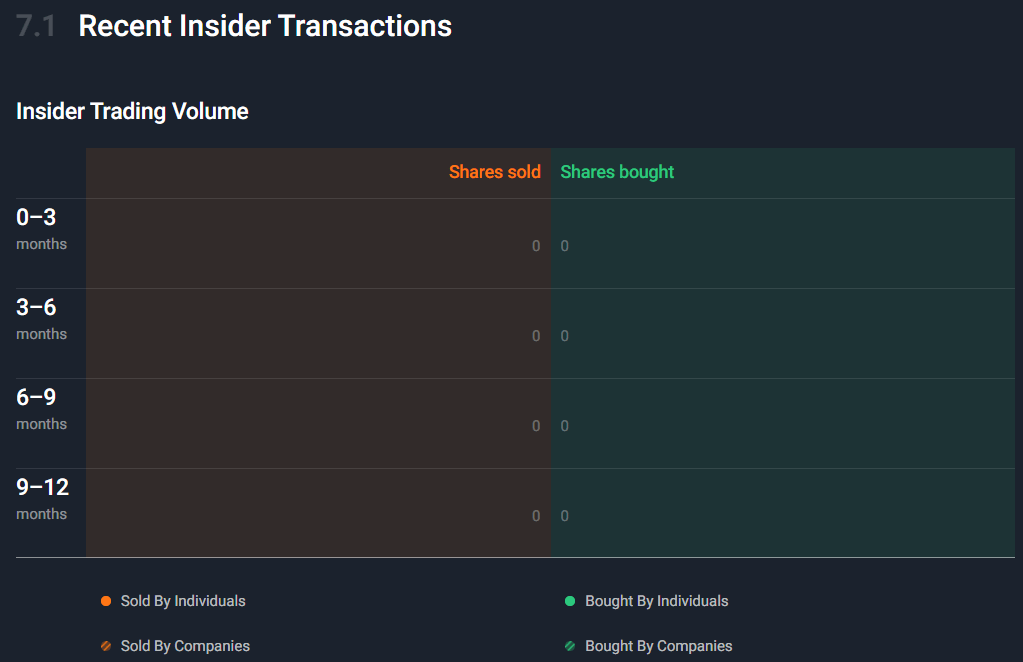
Incentive- This is important because if the current board is buying shares of their own business it indicates that management believes the stock is undervalued and is confident in the company’s long-term prospects.
As you can see below, we have zero buy and sell orders.
Bull And Bear Case:
Bull Case
Bull Case - The first bull case is Jumbo S.A.'s high margins. Jumbo S.A.'s business is built on operational efficiency and a low-price strategy that attracts budget-conscious consumers. This approach results in some of the highest profit margins among European retailers. Jumbo S.A.'s ability to source roughly 70% of products directly from Asia at favourable terms improves its pricing power and profitability.
Bull Case- The second bull case is a diversified product mix. Jumbo S.A. has successfully evolved beyond its origins as a toy retailer. With home goods and seasonal items now its largest segment Jumbo S.A. mitigates its reliance on any single product category. This diverse offering also appeals to a broader year-round customer base.
Bull Case- The third bull case is a long runway for growth. While historically lagging in e-commerce Jumbo S.A. is investing in its online platform and omnichannel strategy. Continued investment in its digital channels offers potential for scalable growth.
Bear Case
Bear Case- The first bear case is their supply chain. Jumbo S.A. sources 70% of its products from Asia (China). This heavy reliance exposes the company to risks associated with geopolitical instability, supply chain disruptions, and fluctuating freight costs. While Jumbo S.A. is investing in logistics its dependence on long-distance sourcing remains a potential vulnerability.
Bear Case- The second bear case is competition. Jumbo S.A. faces growing competition from both international discounters and evolving e-commerce platforms. Despite Jumbo S.A.'s efforts with the e-jumbo platform its digital sales lag significantly behind those of its peers. This underinvestment could erode its long-term competitive position as consumer buying habits continue to shift towards online shopping.
Bear Case- The third bear case is currency fluctuations. The company is exposed to foreign exchange risks particularly with the US Dollar (for sourcing goods) and the Romanian Leu (for local operations). Movements in these currencies can significantly affect financial results.
Valuation:
In this section I will discuss valuation. Using some basic metrics I will compare Jumbo S.A. to its industry rivals and determine whether the company is cheap relative to its peers. Then I will value Jumbo S.A. using a discounted cash flow model to determine a price I am willing to pay based on its expected growth rate and my desired return of 15%.
As shown below when compared to its peers Jumb S.A. scores 3/6 while Pepco Group also scores 3/6. Jumbo S.A. has superior fundamentals compared to Pepco Group and below I am going to highlight the key differences between the companies:
Business Model - Jumbo S.A. operates a big-box hyperstore model. Their strategy is to open large destination stores that act as a central hub. This model relies on high sales volumes per store and allows the company to manage a large and complex inventory. Jumbo S.A.'s approach to expansion is cautious and deliberate where they are opening fewer stores but ensuring each one is dominant in its local market.
Pepco Group uses a deep-discount, small-box retail model that aims for speed and convenience. Their stores are much smaller than Jumbo S.A. This approach allows Pepco Group stores to fit into local neighbourhoods and shopping centres. Pepco Group's primary weapon is its vertical integration in which it manages its entire supply chain through Pepco Global Sourcing (PGS). This means they control the process from factory to shelf which is important for achieving the lowest prices. Pepco Group's growth strategy is aggressive and standardised with a focus on rolling out thousands of stores that look similar to achieve market dominance through proximity and extreme price leadership.
Market Reach- Jumbo S.A.’s market reach is concentrated in Southeastern Europe (SEE). The company is a dominant force in its core markets of Greece, Cyprus, Bulgaria, and Romania. While Jumbo S.A. has a strong local grip its overall geographic expansion is relatively limited and very targeted. They also use franchisees to open stores under the Jumbo name in a few neighbouring countries.
Pepco Group is a Pan-European player. They were built on a foundation of massive growth in Central and Eastern Europe (CEE) particularly in Poland. Over the last few years Pepco Group has rapidly expanded into Western and Southern Europe including Spain, Italy, and more recently into Jumbo S.A.’s territory in Greece. Pepco Group’s strategy is focused on market saturation where they are aiming to be the most visible and accessible discount retailer across as many countries as possible.
Product Offering- Jumbo S.A. is known as the market leader in toys and seasonal goods (such as Christmas or summer decorations) and carries a massive inventory of home decor, stationery, and household necessities. Jumbo S.A. aims to offer a treasure-hunt experience through a constantly changing product selection.
Pepco Group’s product offering is simpler and more focused on basic essentials for families. Their main areas are apparel (clothing for the entire family with children’s wear being a key focus) and essential homeware items. While they do sell general merchandise such as some toys and seasonal items their core expertise is consistently providing low-cost, high-volume basic goods. The company aims to be the go-to shop for routine, budget-friendly needs, rather than specialised or destination shopping.

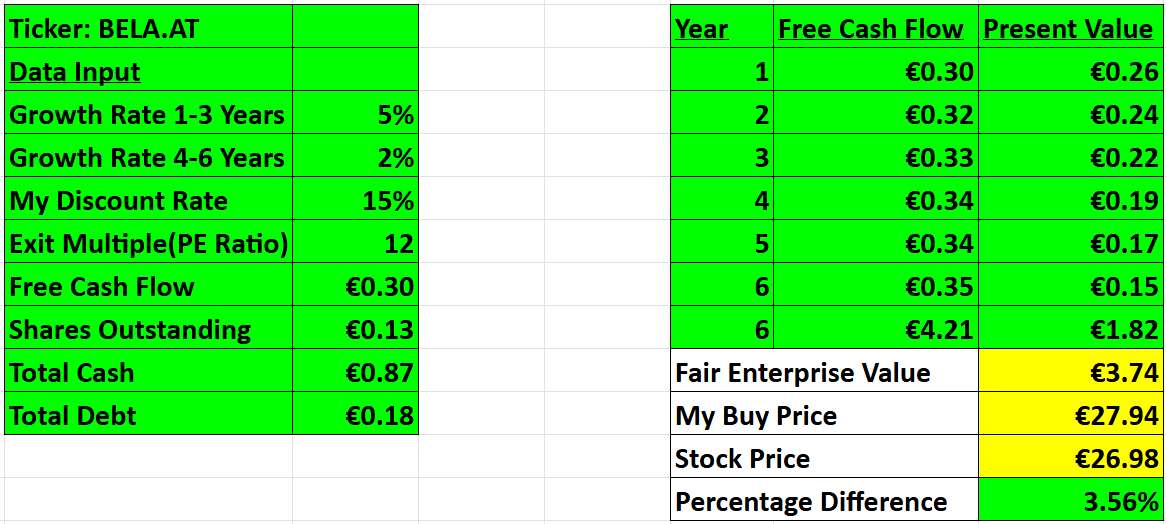
As you can see based on my conservative assumption Jumbo S.A. is looking to grow 7% over the long run so I went conservative and assumed a 5% growth in the first 1-3 years then the growth will slow down to 2% 4-6 years out. In my assumption I also went with an exit multiple of 12x earnings which is below the historical average at which Jumbo S.A. has traded. Based on my assumption I have come to a buy price of €27.74 compared to the current stock price of €26.98 which means right now Jumbo S.A. is trading below its intrinsic value.
Thanks for reading my newsletter on Jumbo S.A. Disclaimer: This newsletter is not financial advice. This is for educational purposes only, so please DO NOT take this as a buy or sell signal.
Follow for more:
Remember to subscribe, share, and comment below if you find this newsletter insightful. Your support helps me continue my work.
Excellent report Wes, I have been consistently adding this one recently.