

Disclaimer: This newsletter is not financial advice it is for educational purposes only. Please DO NOT take this newsletter as a buy or sell signal.
AutoTrader Group Fundamentals:
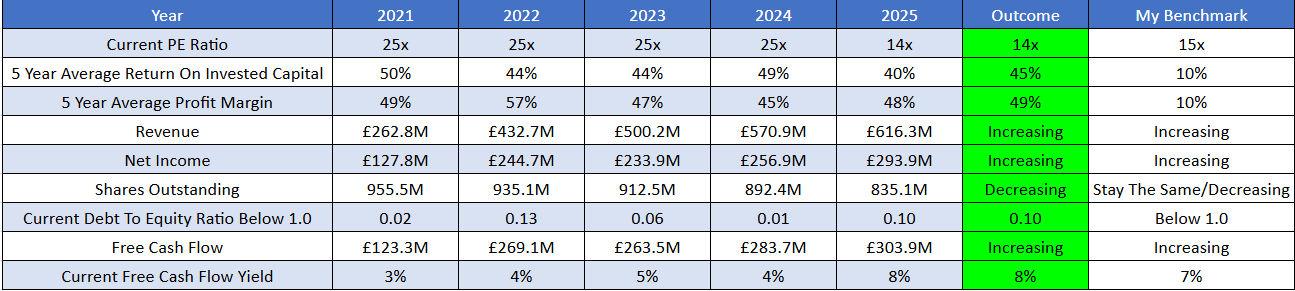
Below is a checklist I normally use when analysing a company’s fundamental health. If the company meets my criteria it will be colour-coded in green and if it fails to meet my criteria it will be colour-coded in red which means I need to investigate further and ask myself why this is the case.
As you can see below AutoTrader Group meets all my criteria.
Business Overview:
Founded in 1977 by Sir John Madejski, Paul Gibbons, and Peter Taylor, Autotrader Group is the UK’s largest digital automotive marketplace and data platform. Autotrader provides a range of services including advanced data and valuations, dealer software solutions such as Auto Trader Connect, and AI-powered retail tools through its Co-Driver toolkit. Following the acquisition of Autorama in 2022 AutoTrader has successfully expanded into new vehicle leasing and end-to-end digital transactions through its Deal Builder technology. By serving as the data-driven backbone for retailers, manufacturers, and lenders Autotrader continues to transform the car-buying and selling process for millions of consumers across the United Kingdom.
Business Segments:
The Autotrader Segment - This is the main business segment of Autotrader Group. This segment is very profitable with an operating profit margin of about 70%. The company’s business model relies on strong network effects as it operates the UK's most-visited automotive site which attracts vehicle sellers. AutoTrader Group generates revenue from trade subscriptions paid by over 14,000 retailers who purchase advertising packages and sophisticated software tools such as Auto Trader Connect and their AI-powered Co-Driver toolkit. Lastly this segment includes Consumer Services which enables private sellers to list vehicles and provides shoppers with instant part-exchange valuations and finance referrals.
Autorama - The Autorama segment which includes the well-known Vanarama brand signifies the group’s strategic shift into the transactional and leasing markets. Unlike the core advertising model Autorama operates as a transactional marketplace focused on the usership model. While this segment has historically operated at lower margins than the core business it has seen significant recovery with losses halving year-on-year as new-vehicle supply stabilised. AutoTrader Group's Autorama segment is integral to their Deal Builder strategy which aims to digitise the entire car-buying journey from initial search to final checkout.
Management:
When evaluating management I judge the CEO based on several factors such as experience, capital-allocation skills, and Incentives. In this section I will discuss whether management incentives are aligned with shareholders.
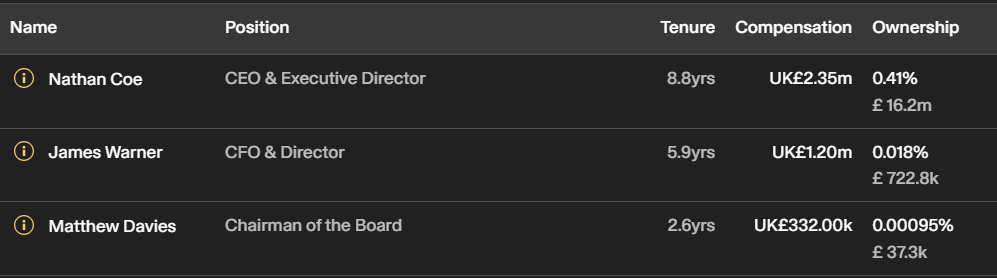
Experience- Nathan Coe has been the Chief Executive Officer of Auto Trader Group since March 2020. Since joining the company in 2007 he has been a pivotal figure in its evolution where he steered the company transition from a traditional magazine business to a pure-play digital powerhouse. He was also instrumental in launching numerous new business areas and led the company’s early entry and subsequent dominance in the mobile and online markets. Nathan Coe holds a Bachelor of Commerce (Honours) from the University of Sydney and began his career as a consultant at PricewaterhouseCoopers (PwC) in Valuations and Strategy. His deep institutional knowledge, financial expertise, and strategic oversight of the company’s digital transformation provide the stability and continuity necessary for AutoTrader Group's ongoing expansion into the transactional and leasing markets.
Below is an image illustrating the current experience of AutoTrader Group board members:
Capital Allocation - Capital allocation is very important when evaluating management because I want them to create value for shareholders not destroy it. So far management has done a great job with capital allocation by providing value back to shareholders. AutoTrader Group utilises its high-margin, asset-light business model to generate significant free cash flow which is then deployed through a disciplined dual-track approach. Management prioritises organic reinvestment in R&D and product development including its AI-powered Co-Driver and Deal Builder tools to maintain its technological advantage. Additionally management provides consistent returns through a progressive dividend policy and aggressive share buybacks which reduce the total share count and increase earnings per share for remaining investors.
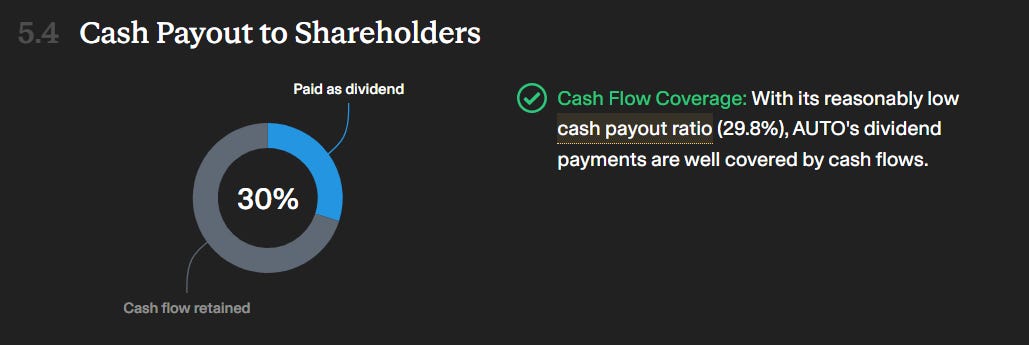
AutoTrader Group currently pays a dividend with a yield of 2.31%. This dividend is sustainable because it only covers 30% of the company’s free cash flow.
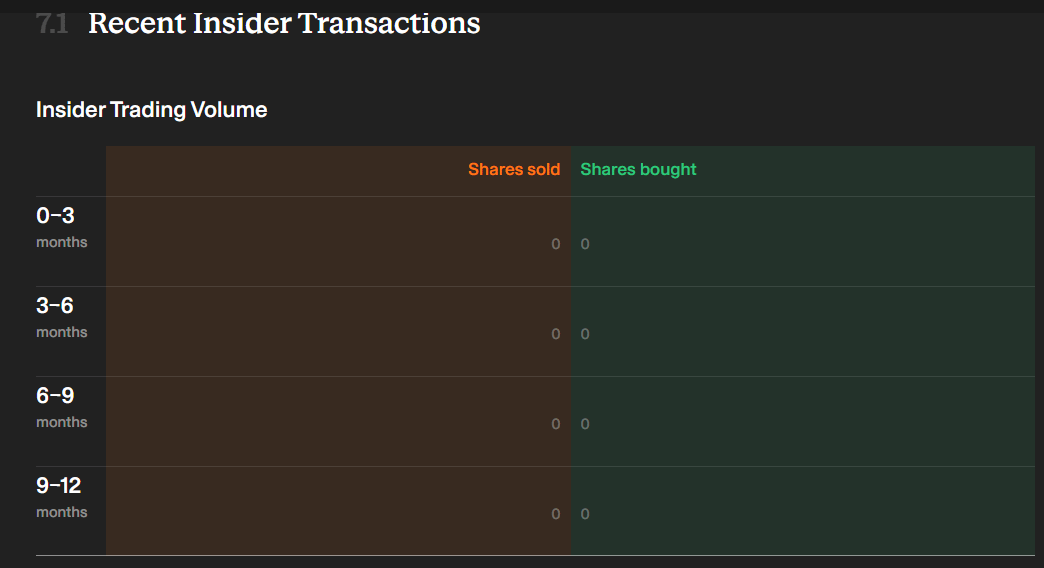
Incentive - This is important because if the current board is buying shares of their own business it indicates that management believes the stock is undervalued and is confident in the company’s long-term prospects.
As you can see below we have zero buy and sell orders.
Bull And Bear Case:
Bull Case
Bull Case - The First bull case is Market Dominance & Audience Lead. AutoTrader Group maintains an overwhelming market share that captures over 75% of all minutes spent on UK automotive marketplaces. This makes it more than 10 times larger than its nearest classified competitor Motors as it ensures it remains the first and only stop for the majority of UK car buyers. This massive scale creates a powerful network effect where the vast majority of car buyers start their journey here effectively forcing over 14,000 retailers to list their stock on the platform to remain competitive. Because AutoTrader Group attracts significantly more traffic than rivals like Motors, Gumtree, and CarGurus combined it possesses unrivalled data supremacy and pricing power. This dominance acts as a high barrier to entry as any new competitor would require immense marketing spend to disrupt the ingrained consumer habit of visiting AutoTrader Group first.
Bull Case - The Second bull case is AI Monetisation Via Co-Driver. Launched in 2025 the Co-Driver generative AI toolkit is now used by over 10,000 retailers. It automates the creation of high-quality vehicle adverts (over 1 million to date) which directly justify annual price increases and boost Average Revenue Per Retailer (ARPR).
Bull Case - The Third bull case is Unrivalled Proprietary Data Moat. Autotrader Group tracks more real-time transactions than anyone else. It is so influential that the Office for National Statistics (ONS) continues to use it as a component of its inflation measurement making the platform's valuation tools indispensable for dealers.
Bear Case
Bear Case - The First bear case is Supply Chain Issues. The most immediate risk in 2026 is a projected 25–30% decline in the availability of 5- to 7-year-old vehicles. This is a direct result of the pandemic production gap in which millions of new cars were not manufactured. Since this age bracket is a high-volume segment for Autotrader Group retail partners a lack of stock could reduce the total number of paid listings on the platform.
Bear Case - The Second bear case is Regulatory Scrutiny. The UK’s Motor Finance Redress Scheme remains a major headwind for the industry in 2026. As the FCA finalises rules regarding historical commission structures many of AutoTrader Group’s dealer partners face significant financial liabilities and operational costs which could lead to reduced marketing budgets or even dealership closures.
Bear Case - The Third bear case is Continued Losses at Autorama. Despite narrowing losses the Autorama (Vanarama) segment remains a drag on the group’s overall profit margins. The transition from a high-margin advertising model to a lower-margin capital-intensive leasing model carries execution risks especially if borrowing costs remain elevated for consumers.
Valuation:
In this section I will discuss valuation. Using some basic metrics I will compare AutoTrader Group to its industry rivals and determine whether the company is cheap relative to its peers. Then I will value AutoTrader Group using a discounted cash flow model to determine a price I am willing to pay based on its expected growth rate and my desired return of 15%.
As shown below when compared to its peers AutoTrader Group scores 2/5 while Cargurus scores 3/5. Below I am going to highlight the key differences between the companies:
Business Model - Auto Trader operates a high-margin, subscription-based software-and-advertising model that provides the essential digital infrastructure for the UK automotive market. Over 14,000 retailers pay monthly fees for advertising slots and advanced data tools resulting in high operating profit margins of approximately 70%. The focus for AutoTrader Group remains on growing Average Revenue Per Retailer (ARPR) which has reached roughly £3,000 per month in 2026. This growth is driven by the adoption of sophisticated, high-margin software such as Auto Trader Connect and the AI-powered Co-Driver toolkit which allows the company to scale without the costs of holding physical inventory.
CarGurus utilises a transparency-first model that effectively blends dealer subscriptions with a specialised focus on lead generation. Unlike a traditional classifieds model CarGurus ranks listings using a proprietary algorithm that labels vehicles as Great, Good, or Fair deals which is central to building consumer trust. n the UK CarGurus acts as a challenger brand that utilises a more flexible model to attract retailers looking for a data-led alternative. While its global operating margins are healthy (typically around 30–35%), they remain lower than those of AutoTrader Group.
Market Reach - AutoTrader Group maintains an overwhelming market share that captures over 75% of all minutes spent on UK automotive marketplaces. This dominance creates a powerful network effect because two-thirds of UK car buyers exclusively use Auto Trader Group which means retailers are effectively forced to maintain a presence on the site to reach the vast majority of the market.
CarGurus is a significant secondary player in the UK capturing a smaller but highly engaged segment of the market. In the UK it typically sees between 8 and 10 million visits per month. While it is a global leader especially in the US its UK reach is primarily driven by consumers who want to verify pricing through its Instant Market Value tool. CarGurus has reported that a substantial portion of its monthly visitors shop exclusively on its platform suggesting it has carved out a loyal, high-intent audience that values its algorithmic transparency over the broader reach of larger rivals.
Product Offering - AutoTrader Group portfolio includes used and new cars, vans, bikes, and motorhomes. AutoTrader Group is currently leading the transition to Full Digital Retailing through its Deal Builder tool which has seen rapid adoption with over 4,000 retailers live by early 2026. This product allows buyers to complete finance applications and part-exchange valuations online. Additionally the company provides deep security through its 26-point independent vehicle history checks positioning itself as a high-trust, end-to-end ecosystem rather than just a listing site.
CarGurus specialises in data-driven services that primarily target the used car and van markets. One of its standout features is the AI-powered CG Discover assistant which helps users find vehicles using natural-language queries. Additionally CarGurus offers a Dealership Mode that assists shoppers while they are on a dealership lot. CarGurus has emphasised that its high-value transactional leads convert at a rate 4.7 times higher than standard marketplace leads. This makes its offerings particularly appealing to dealers looking for ready-to-buy shoppers who have already begun the financing and trade-in processes.

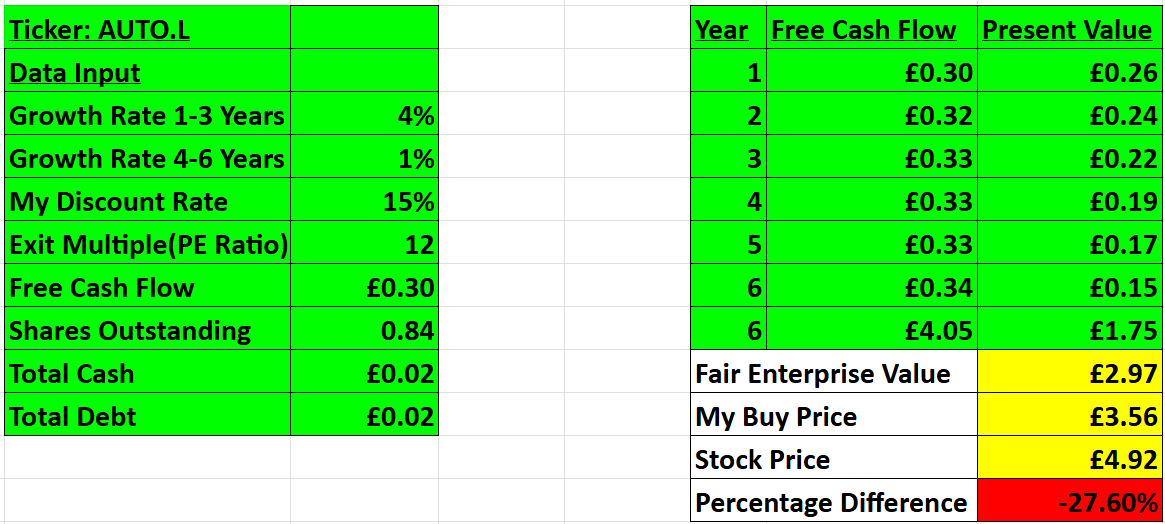
As you can see based on my conservative assumption AutoTrader Group is looking to grow 6% over the long run so I went conservative and assumed a 4% growth in the first 1-3 years then the growth will slow down to 1% 4-6 years out. In my assumption I also went with an exit multiple of 12x earnings which is below the historical average at which AutoTrader Group has traded. Based on my assumption I have come to a buy price of £3.56 compared to the current stock price of £4.92 which means right now AutoTrader Group is trading above its intrinsic value.
Thanks for reading my newsletter on AutoTrader Group.
Disclaimer: This newsletter is not financial advice. This is for educational purposes only, so please DO NOT take this as a buy or sell signal.
Follow for more:
Remember to subscribe, share, and comment below if you find this newsletter insightful. Your support helps me continue my work.
12x feels incredibly harsh. Nice write up, by the way. I’m not a holder as despite thinking it’s a fantastic company, it falls into the slower growing near-monopoly bucket as Trainline and Rightmove in the UK, for me. No meaningful acquisition history too.
Auto Trader is a prime example of a network effect moat. Its 70%+ operating margins and high Return on Equity demonstrate the power of a "capital-light" digital platform: once the infrastructure is built, incremental revenue scales with almost no additional cost. By integrating AI-driven tools like "Co-Driver," they are effectively using their massive proprietary dataset to lock in retailers and widen their competitive advantage over smaller marketplaces.
As new EV manufacturers shift toward direct-to-consumer sales, do you think Auto Trader’s expansion into digital retailing tools (like "Deal Builder") will be enough to offset the potential decline in traditional dealership listings?